 UCG.org
Could the Dollar Fall?
Several recent headlines in London's Financial Times
illustrate a continuing thought among world financial leaders. The first
headline said, “Brazil and China Eye Plan to Axe Dollar.” “China
Attacks Dollar's Dominance” read another. A third spoke of
“De-Dollarization and the Ending of America's Financial-Military
Hegemony.” Another spotlighted the lack of confidence in American
financial leadership: “Dollar Falls as Geithner [the U.S. Treasury Secretary] Hails Recovery Hopes.”
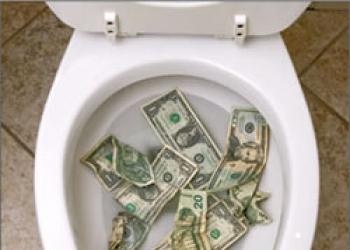
Warning shots are being fired across America's bow. Many want an end to the era of the dollar as the world's reserve currency. If that happens, your financial world will be forever altered.
China is concerned that the U.S. Treasury bills (T-bills) and bonds it holds will lose much of their worth if the dollar is devalued or the financial crisis does not turn around.
By calling for the creation of another reserve currency, China, Russia and other nations seek insurance for their economies against the problems generated when one country's economy goes bad. They also seek to end American dominance over the world economy. America's decline and China's rise fit their geopolitical ambitions.
Ending the dollar's role in the world economy is not an easy matter. The Wall Street Journal stated: “The technical and political hurdles to implementing China's recommendation [to create a new standard world currency to replace the dollar] are enormous, so even if backed by other nations, the proposal is unlikely to change the dollar's role in the short term.
“Central banks around the world hold more U.S. dollars and dollar securities than they do assets denominated in any other individual foreign currency. Such reserves can be used to stabilize the value of the central banks' domestic currencies” (“China Takes Aim at Dollar,” March 24, 2009).
Although the current financial problems ignited in America have led to a global meltdown, it will take more than what we've experienced so far to topple America from its current role. That is not to say this could not or will not happen.
Creating another world currency requires several factors to be in place. Research analysts at the private intelligence agency Stratfor outlined what those factors would be:
“As to a world beyond the dollar, the issue is that a reserve currency is not decided upon; it creates itself. Two things are needed to create a reserve currency. First, there must be sufficient liquidity to support a global system. That requires a central bank with an enormous amount of autonomy from a state government, and the U.S. Federal Reserve is unparalleled on this count. Not even the European Central Bank can compete.
“Second, the economy upon which the currency is based must be large enough to withstand fluctuations caused by other economies buying and selling its assets in massive amounts. Again, the United States is the only economy that potentially could qualify.
“Part and parcel of any replacement of the U.S. dollar would be a large-scale abandonment of U.S. T-bills as the core of Chinese currency reserves, which—as the conventional wisdom holds—would force intractable economic problems upon the United States. But a closer look reveals that this is not the case.
“First, selling U.S. T-bills en masse simply is not possible. Every seller requires a buyer, and the volumes at hand cannot be exchanged quickly. Second, starting down that road would cause the value of the securities in question to plummet, destroying the savings the Chinese have been building up for years. The so-called 'nuclear option' really is not an option at all” (“China's Calculated Currency Rhetoric,” March 25, 2009).
China has its own problems. The huge middle class created by their recent boom is beginning to experience layoffs and financial setbacks. The ruling Communist Party cannot afford discontent from this segment of its society. Once people have tasted materialism, they won't go back. For now it's in China's interest to blame a foreign power (America). It deflects attention from the home front.
Yet clearly, China is playing a very dangerous geopolitical game with calls for a new reserve currency.
So what would it mean for the American consumer if the dollar were no longer the world's reserve currency?
Everything Americans import would cost more— everything. Americans would have to buy the new currency in order to trade in world markets. Last year's $4-per-gallon gasoline would quickly look like a bargain.
The credit market would collapse. Investors would flee toxic assets, further locking up the economy.
The U.S. Federal Reserve would print more money to combat the credit squeeze, with the likely result being hyperinflation, meaning higher prices for available goods. Remember the stories of Weimar Germany after World War I when it took a wheelbarrow full of money to buy a loaf of bread? Not pretty.
American power and influence in the world would seriously decline. Little understood today is the role of the economy in shaping and controlling world events. The dollar's place in the world adds incalculable weight to American influence. With the dollar diminished, that influence would be reduced substantially. Russia and China are waiting for their turn to assume that power, but they would certainly meet with competition from the European Union.
Big losers from the fall of the dollar would include Japan and Latin America. Because they hold much of America's debt, China and the oil-rich Persian Gulf states would also see huge losses. Israel and Egypt would suffer as well because of massive amounts of American aid they would lose. What this would mean to the Middle East calculus is unknown, but Egypt could be destabilized as a result.
World politics would be altered. The vacuum of power created would be contested. The EU, which stands to gain from the fall of the dollar, would be among the chief contenders. China would no doubt make a play as well, but a number of factors would hinder its bid. Stability would arise from the potential period of chaos with another power becoming the global economy's main engine. America's time in the sun would be over.
American lifestyles would change radically. The end of cheap oil, low interest rates and deficit spending would mean a lower quality of life and higher taxes. What this would mean to the social fabric of the nation is unknown. But Americans' way of life would dramatically change.
This last point speaks to the character of the American people. Do they have the same qualities that helped a prior generation survive the upheaval of a Great Depression and World War II?
For one, America's crippling foreign debt would get worse with decreased ability to finance the burden. In time the country would be at the mercy of those holding its obligations, with little room to maneuver. Economic enslavement to other nations would be on the horizon.
However, it's unlikely that this will happen immediately. China and several Arab states hold too many dollar-denominated instruments to see this change. As mentioned, they would lose too much. Right now the United States is too big, too rich and too powerful for them to allow it to fail. There is too much at stake on the global scene.
That does not mean things couldn't change—and change quickly—but the proper circumstances have to be in place.
It will not happen until the God of heaven allows it to happen. God has blessed America with its wealth, power and resulting prestige. He will move to change that when it fits His timing for His great plan for all the nations.
Until then we have days to live and many lives to touch. We have character to develop and mistakes to correct. We have days to love those close to us and, above all, time to discover God and His attention to the details of eternity, history and our lives. Make the most of the time while you can. GN
Warning shots are being fired across America's bow. Many want an end to the era of the dollar as the world's reserve currency. If that happens, your financial world will be forever altered.
Could this happen?
The United States is now the world's largest debtor nation ($10.6 trillion). And China owns more of that debt than any other nation—more than $800 billion. Chinese Premier Wen Jiabao has publicly expressed “worries” over China's significant holdings of U.S. government bonds, which ties China to America's good times and its bad times.China is concerned that the U.S. Treasury bills (T-bills) and bonds it holds will lose much of their worth if the dollar is devalued or the financial crisis does not turn around.
By calling for the creation of another reserve currency, China, Russia and other nations seek insurance for their economies against the problems generated when one country's economy goes bad. They also seek to end American dominance over the world economy. America's decline and China's rise fit their geopolitical ambitions.
Ending the dollar's role in the world economy is not an easy matter. The Wall Street Journal stated: “The technical and political hurdles to implementing China's recommendation [to create a new standard world currency to replace the dollar] are enormous, so even if backed by other nations, the proposal is unlikely to change the dollar's role in the short term.
“Central banks around the world hold more U.S. dollars and dollar securities than they do assets denominated in any other individual foreign currency. Such reserves can be used to stabilize the value of the central banks' domestic currencies” (“China Takes Aim at Dollar,” March 24, 2009).
Will the dollar's reign soon end?
Before the dollar, the British pound sterling formed the underpinning of the global economy. It took two world wars and several decades for the world standard to shift from the pound to the dollar. Since the end of World War II, the dollar has been king.Although the current financial problems ignited in America have led to a global meltdown, it will take more than what we've experienced so far to topple America from its current role. That is not to say this could not or will not happen.
Creating another world currency requires several factors to be in place. Research analysts at the private intelligence agency Stratfor outlined what those factors would be:
“As to a world beyond the dollar, the issue is that a reserve currency is not decided upon; it creates itself. Two things are needed to create a reserve currency. First, there must be sufficient liquidity to support a global system. That requires a central bank with an enormous amount of autonomy from a state government, and the U.S. Federal Reserve is unparalleled on this count. Not even the European Central Bank can compete.
“Second, the economy upon which the currency is based must be large enough to withstand fluctuations caused by other economies buying and selling its assets in massive amounts. Again, the United States is the only economy that potentially could qualify.
“Part and parcel of any replacement of the U.S. dollar would be a large-scale abandonment of U.S. T-bills as the core of Chinese currency reserves, which—as the conventional wisdom holds—would force intractable economic problems upon the United States. But a closer look reveals that this is not the case.
“First, selling U.S. T-bills en masse simply is not possible. Every seller requires a buyer, and the volumes at hand cannot be exchanged quickly. Second, starting down that road would cause the value of the securities in question to plummet, destroying the savings the Chinese have been building up for years. The so-called 'nuclear option' really is not an option at all” (“China's Calculated Currency Rhetoric,” March 25, 2009).
China has its own problems. The huge middle class created by their recent boom is beginning to experience layoffs and financial setbacks. The ruling Communist Party cannot afford discontent from this segment of its society. Once people have tasted materialism, they won't go back. For now it's in China's interest to blame a foreign power (America). It deflects attention from the home front.
Yet clearly, China is playing a very dangerous geopolitical game with calls for a new reserve currency.
What would it mean for Americans?
Since the end of World War II, the dollar has been the dominant world currency. For most living Americans, this is the world into which they were born. This is all they have known. Americans enjoy one of the world's highest living standards due to the stability and wealth created by America's dominant economic role.So what would it mean for the American consumer if the dollar were no longer the world's reserve currency?
Everything Americans import would cost more— everything. Americans would have to buy the new currency in order to trade in world markets. Last year's $4-per-gallon gasoline would quickly look like a bargain.
The credit market would collapse. Investors would flee toxic assets, further locking up the economy.
The U.S. Federal Reserve would print more money to combat the credit squeeze, with the likely result being hyperinflation, meaning higher prices for available goods. Remember the stories of Weimar Germany after World War I when it took a wheelbarrow full of money to buy a loaf of bread? Not pretty.
American power and influence in the world would seriously decline. Little understood today is the role of the economy in shaping and controlling world events. The dollar's place in the world adds incalculable weight to American influence. With the dollar diminished, that influence would be reduced substantially. Russia and China are waiting for their turn to assume that power, but they would certainly meet with competition from the European Union.
Big losers from the fall of the dollar would include Japan and Latin America. Because they hold much of America's debt, China and the oil-rich Persian Gulf states would also see huge losses. Israel and Egypt would suffer as well because of massive amounts of American aid they would lose. What this would mean to the Middle East calculus is unknown, but Egypt could be destabilized as a result.
World politics would be altered. The vacuum of power created would be contested. The EU, which stands to gain from the fall of the dollar, would be among the chief contenders. China would no doubt make a play as well, but a number of factors would hinder its bid. Stability would arise from the potential period of chaos with another power becoming the global economy's main engine. America's time in the sun would be over.
American lifestyles would change radically. The end of cheap oil, low interest rates and deficit spending would mean a lower quality of life and higher taxes. What this would mean to the social fabric of the nation is unknown. But Americans' way of life would dramatically change.
This last point speaks to the character of the American people. Do they have the same qualities that helped a prior generation survive the upheaval of a Great Depression and World War II?
America losing the pride of her power?
Those pushing to create a different world are no doubt working hard to bring about the demise of the dollar and the end of America's dominant role in the world. In The Good News we have spoken before of America's prophesied loss of “the pride of [its] power” (Leviticus 26:19). While military might is what we think of first in this regard, economic factors are also important here. The dollar losing its reserve currency status would radically change America's leading role in the world.For one, America's crippling foreign debt would get worse with decreased ability to finance the burden. In time the country would be at the mercy of those holding its obligations, with little room to maneuver. Economic enslavement to other nations would be on the horizon.
However, it's unlikely that this will happen immediately. China and several Arab states hold too many dollar-denominated instruments to see this change. As mentioned, they would lose too much. Right now the United States is too big, too rich and too powerful for them to allow it to fail. There is too much at stake on the global scene.
That does not mean things couldn't change—and change quickly—but the proper circumstances have to be in place.
It will not happen until the God of heaven allows it to happen. God has blessed America with its wealth, power and resulting prestige. He will move to change that when it fits His timing for His great plan for all the nations.
Until then we have days to live and many lives to touch. We have character to develop and mistakes to correct. We have days to love those close to us and, above all, time to discover God and His attention to the details of eternity, history and our lives. Make the most of the time while you can. GN



 Posts


